
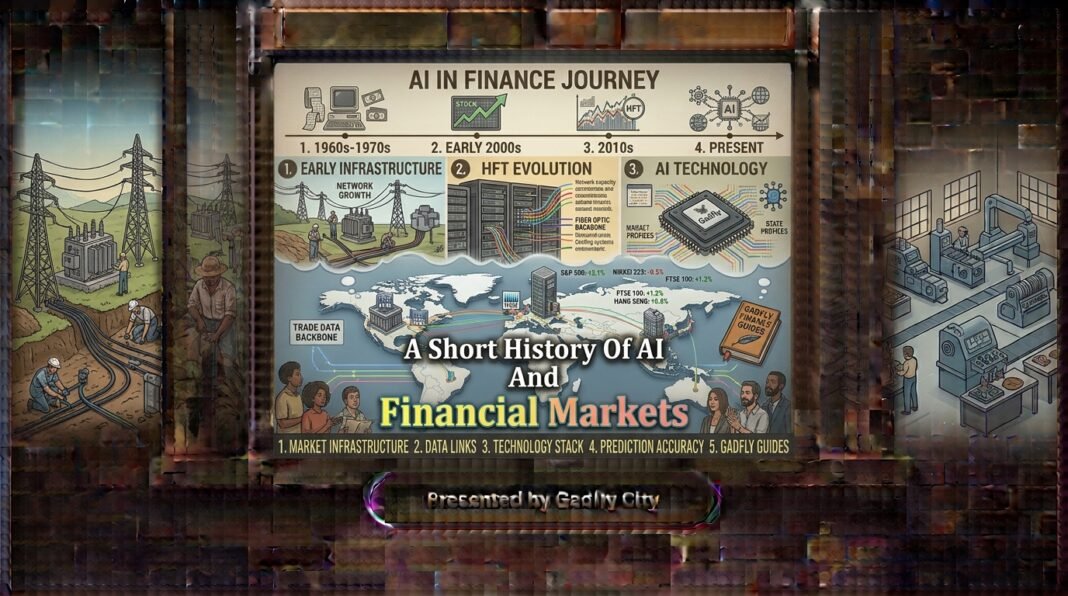
The history of AI in financial markets is a story of technological progress, faster trading, and growing risks for everyday investors. From early mathematical models to high-frequency trading and modern machine learning, Wall Street has used automation to gain an advantage. But when algorithms interact under pressure, their speed can amplify losses, expose weaknesses, and leave ordinary investors facing consequences they cannot control.
Key Takeaways
- Financial markets adopted computer-driven trading long before modern generative AI became popular.
- Broker-dealers, hedge funds, and proprietary trading firms use algorithms to analyze data, execute orders, and exploit short-lived price differences.
- The May 2010 Flash Crash demonstrated how automated trading could amplify market instability.
- The August 2015 market disruption exposed weaknesses in market openings, liquidity, and exchange-traded products.
- Algorithmic trading is not always AI, and automation does not automatically cause market manipulation or crashes.
- Regulators such as the SEC, CFTC, and FINRA have oversight roles, but investors still face risks that regulation cannot eliminate.
How The History Of AI Began In Financial Markets
The history of AI began long before investors could ask a chatbot to analyze a stock. In 1956, researchers at Dartmouth helped establish artificial intelligence as a formal field of study. Financial markets subsequently developed increasingly sophisticated computer models using statistics, probability, and mathematical optimization.
Early trading systems were not necessarily intelligent in the modern sense. They followed programmed instructions, calculated prices, and processed market information. However, these foundations helped create the automated financial systems that now influence how securities are bought and sold.
The Cold War also accelerated developments in computing, strategic analysis, and operations research. These ideas influenced fields such as economics and quantitative finance. Our article on who was primarily responsible for the Cold War provides historical context for the geopolitical environment in which many modern computing disciplines developed.
From Open-Outcry Pits To Automated Trading
For decades, traders bought and sold financial contracts through open-outcry trading pits, communicating orders through hand signals and shouted bids. Human judgment, physical presence, and the speed of communication shaped the trading process.
Electronic markets gradually changed that system. Computers could process orders faster, compare prices across exchanges, and execute trades without a person manually handling each transaction. As electronic trading expanded, financial firms increasingly competed on computing power, data quality, and execution speed.
This transition created opportunities for broker-dealers, hedge funds, and proprietary trading firms. A broker-dealer may use algorithms to execute client orders efficiently, while a hedge fund might use quantitative models to identify investment opportunities. Proprietary trading firms use their own capital to pursue profits from market movements and pricing differences.
High-frequency trading (HFT) takes automation further by executing large numbers of orders at extremely high speeds. Some firms use sophisticated statistical models or machine learning, but many HFT strategies rely on conventional, rules-based algorithms rather than AI.
That distinction matters. The history of AI overlaps with algorithmic trading, but the two are not interchangeable. Both can influence prices, liquidity, and the experience of ordinary investors.
The May 2010 Flash Crash: When Algorithms Amplified The Sell-Off
The May 6, 2010, Flash Crash remains one of the clearest warnings in the history of AI and automated finance. Within minutes, U.S. stock markets experienced extraordinary price declines, followed by a substantial recovery. The Dow Jones Industrial Average fell nearly 1,000 points from its previous close at its intraday low before recovering much of that loss.
According to the SEC’s examination of the May 2010 market plunge, a large automated sell order in E-mini S&P 500 futures contributed to a chain of events involving other market participants. High-frequency traders responded to changing conditions, while liquidity weakened and selling pressure spread across connected markets.
The important lesson is not that AI single-handedly caused the crash. Investigators identified several interacting factors, including the large sell order, automated trading responses, market fragmentation, and the withdrawal of liquidity. The episode showed how computer systems designed to execute trades efficiently could collectively contribute to disorderly markets.
For ordinary investors, the consequences were tangible. Some securities traded at wildly distorted prices, and certain transactions were subsequently canceled under exchange procedures. Investors using market orders or automated stop-loss orders could be exposed to prices far removed from their expectations.
The history of AI in finance therefore includes a difficult question: when automated systems behave unexpectedly, who bears the cost?
August 2015: Another Warning About Automated Markets
On August 24, 2015, U.S. stocks and exchange-traded products experienced severe volatility around the market opening. Some exchange-traded funds traded at substantial discounts to their underlying assets, while trading halts interrupted activity in numerous securities.
The SEC’s research note on August 24 market volatility examined the relationship between market conditions and the unusually volatile behavior of exchange-traded products. The analysis highlighted the importance of liquidity, opening auctions, and trading halts rather than establishing that AI alone caused the disruption.
The distinction matters because the history of AI should not become a convenient explanation for every market decline. Automated trading can transmit price movements rapidly, but poor liquidity, uncertainty, market structure, and human decisions also influence outcomes.
Nevertheless, the episode reinforced a recurring concern: when markets open under pressure, automated systems may struggle to price assets reliably. Investors who expect an ETF to trade close to its underlying value can face unexpected execution prices when the market becomes dislocated.
Who Regulates AI Trading, And Does It Protect Main Street?
In the United States, responsibility is distributed across several organizations. The Securities and Exchange Commission (SEC) oversees securities markets, while the Commodity Futures Trading Commission (CFTC) regulates futures and other derivatives within its jurisdiction. The Financial Industry Regulatory Authority (FINRA) supervises member broker-dealers and enforces applicable industry rules.
FINRA has issued guidance on supervising algorithmic trading strategies, covering areas such as testing, software changes, risk controls, and ongoing monitoring. This shows that regulators recognize algorithmic systems can create risks for firms and markets.
However, supervision is not the same as a guarantee of protection. Regulators investigate misconduct, establish requirements, and take enforcement action where appropriate, but they cannot eliminate every technical failure, unexpected market interaction, or investment loss. Nor does every automated trading loss represent a regulatory violation.
Critics reasonably question whether oversight can keep pace with increasingly complex trading systems. The concern is especially relevant when sophisticated firms have better technology and more detailed market data than ordinary investors.
A balanced view of the history of AI recognizes both sides: automation can improve execution and market efficiency, but its benefits and risks are not necessarily distributed equally.
How AI Can Affect Everyday Investors
The impact often appears indirectly rather than as an obvious charge on a brokerage statement. Automated trading can influence execution prices, short-term volatility, spreads, and the availability of buyers when investors want to sell.
During unstable conditions, a market order may execute at a worse price than expected. Stop-loss orders can also become market orders once triggered, potentially exposing investors to sharp price movements. Frequent trading adds another problem: transaction costs and poor timing can steadily reduce returns.
AI models also analyze economic data, company announcements, and consumer behavior. These tools can influence expectations about inflation, interest rates, and corporate earnings. Understanding why inflation makes your paycheck feel smaller provides useful context for the economic forces that trading models attempt to interpret.
Investors should also distinguish legitimate quantitative strategies from manipulation. Not every fast trade is abusive, and not every market loss is caused by an algorithm. The practical response is to understand order types, diversify appropriately, avoid relying on guaranteed-return claims, and treat automated trading promises with skepticism.
The broader history of AI offers a simple lesson: technology can process information faster, but it cannot make financial uncertainty disappear.
What The History Of AI Means For The Future Of Finance
Today’s AI systems can identify patterns in enormous datasets, estimate probabilities, and adapt models using historical information. Financial firms may use these capabilities for research, portfolio construction, fraud detection, and risk management. Yet a model trained on yesterday’s market can still fail when tomorrow brings unfamiliar conditions.
The same principle applies to automated trading. Speed is useful when executing a sensible strategy, but it can magnify mistakes when assumptions break down. Effective safeguards require independent testing, human oversight, clear accountability, and systems capable of stopping dangerous activity.
We should also resist treating every new AI product as a breakthrough. FINRA has warned investors about automated trading services that exaggerate AI capabilities or promise unrealistic returns. Before trusting a platform, investors should verify its registration, understand its fees, and investigate how it manages risk.
Ultimately, the history of AI in financial markets is not simply a story of machines replacing people. It is a story of how technology changes incentives, concentrates advantages, and creates new responsibilities. The real measure of progress should not be how quickly a computer can trade, but whether markets remain fair, resilient, and understandable to the people whose savings depend on them.
Frequently Asked Questions
1. When Did AI First Begin Influencing Financial Markets?
AI research became an established field in 1956, but financial markets adopted computer-based quantitative methods and automated trading over subsequent decades. Modern machine learning expanded these capabilities, particularly as computing power and market data improved.
2. Did AI Cause The May 2010 Flash Crash?
No single cause explains the May 2010 Flash Crash. Investigators identified a large automated futures sell order, changing high-frequency trading activity, and deteriorating liquidity as interacting factors that contributed to the extraordinary market disruption.
3. What Happened During The August 2015 Market Disruption?
On August 24, 2015, U.S. markets experienced severe opening volatility, trading halts, and unusual exchange-traded product prices. The episode highlighted weaknesses in market-opening procedures, liquidity, and market structure under stressful conditions.
4. Does FINRA Protect Investors From AI Trading Risks?
FINRA supervises member broker-dealers and issues guidance on algorithmic trading controls. However, its oversight cannot prevent every market disruption, technical failure, or investment loss, and other regulators have separate responsibilities across financial markets.
5. Can AI Trading Algorithms Manipulate Stock Prices?
Algorithms can be used in legitimate trading or in prohibited practices such as spoofing and layering. Whether conduct constitutes manipulation depends on the circumstances, intent, applicable rules, and evidence—not simply on whether a computer executed the trades.
6. How Can Everyday Investors Reduce Algorithmic Trading Risks?
Investors can use appropriate order types, diversify their portfolios, understand brokerage fees, and avoid making decisions based on sudden price movements alone. They should also verify financial service providers and remain skeptical of guaranteed AI trading returns.
Conclusion: A Smarter Market Needs More Than Smarter Machines
At Gadfly City, we believe understanding financial technology means examining not only what it can accomplish, but also who benefits and who carries the risks. Our perspective is that innovation deserves scrutiny alongside its promises. As the history of AI continues to unfold, informed investors and meaningful accountability will remain essential to building markets that serve more than the fastest participants.
Sources And References
- Dartmouth – The Founding And Future Of AI
- U.S. Securities And Exchange Commission – Examining The Causes And Lessons Of The May 6th Market Plunge
- U.S. Securities And Exchange Commission – Research Note: Equity Market Volatility On August 24, 2015
- FINRA – Regulatory Notice 15-09: Effective Supervision And Control Practices For Algorithmic Trading Strategies
- FINRA – Know The Risks Of Auto-Trading Services Offered By Unregistered Entities
- U.S. Securities And Exchange Commission – Market Participants And The May 6 Flash Crash